

Yes. Sunscreen is FSA eligible: broad-spectrum sunscreen with SPF 15 or higher can be bought with a health FSA or HSA, with no prescription, since the 2020 CARES Act.
Is sunscreen FSA eligible in every account, though? Not quite. The answer depends on the type of account, the wording on the label and, for anything beyond sunscreen, a clinician's paperwork.
Timing matters too. Health FSA money is generally "use it or lose it" at the end of the plan year, which is why November and December are when balances get spent. This guide covers what qualifies, which accounts pay, what UV umbrellas and UPF products need, how HSA and FSA cards work at UV-Blocker, and the 2026 deadline rules.
Is Sunscreen FSA Eligible, and What Qualifies?
Yes. Broad-spectrum sunscreen with SPF 15 or higher is an eligible health FSA expense, with no prescription needed, because over-the-counter products became reimbursable under the 2020 CARES Act.
Under the CARES Act, over-the-counter products and medications became reimbursable from HSAs, FSAs and HRAs without a prescription, for amounts paid after Dec. 31, 2019. The IRS set out the change in news release IR-2020-122 on June 17, 2020.
The IRS does not publish a list that names sunscreen. Sunscreen qualifies because it is regulated as a drug in the United States, so it sits in the same over-the-counter category as other nonprescription medicines.
Where the SPF 15 and broad-spectrum line comes from
The line comes from FDA labeling rules, not from the tax code.
According to the FDA, sunscreens that are not broad spectrum, or that have an SPF below 15, must carry a warning that they have "been shown only to help prevent sunburn, not skin cancer or early skin aging."
That warning marks the line administrators and retailers commonly use to decide which sunscreens count. A product labeled Broad Spectrum SPF 15 or higher clears it.
Which sunscreens usually qualify
- Usually eligible: lotions, sprays, sticks, mineral sunscreens, kids' sunscreens and tinted sunscreens, when they are labeled broad spectrum SPF 15+ and sold as sunscreen.
- Depends on the administrator: moisturizers and foundations with SPF that are sold mainly as cosmetics. Some plans decline them.
- Not eligible: tanning oils and any product under SPF 15 or without broad-spectrum protection.
Keep itemized receipts that show the product name, not just a store total. Which account pays matters as much as the product:
| Account | Pays for broad-spectrum SPF 15+ sunscreen? | Notes |
|---|---|---|
| Health care FSA (general purpose) | Yes, no prescription | Generally use it or lose it; 2026 limit $3,400 |
| HSA | Yes, no prescription | Money rolls over year to year; 2026 limits $4,400 self-only, $8,750 family |
| Limited-purpose FSA | Generally no | Usually limited to dental and vision; check your plan |
| Dependent care FSA | No | Pays for child or adult dependent care, not health products |
| HRA | Only if the employer's plan covers OTC items | The employer sets what it covers |
The HSA has one important difference: time.
Is Sunscreen HSA Eligible Too?
Yes. HSA eligible sunscreen follows the same rule: broad-spectrum SPF 15+ sunscreen is a qualified medical expense, and unlike an FSA, unspent HSA money stays in your account.
The CARES Act change covers HSAs as well as FSAs, so the same sunscreens qualify. HSA money does not expire, so an HSA owner has no year-end deadline to beat.
The trade-off is recordkeeping. IRS Publication 969 says HSA owners must keep records showing that distributions paid for qualified medical expenses. Money taken out for anything else is taxed as income and may face an additional 20% tax.
When the FSA can't pay but the HSA can
An HSA owner generally can't also be covered by a general-purpose health FSA, so the FSA offered alongside an HSA is usually a limited-purpose one, restricted to dental and vision care. In that case, sunscreen should come out of the HSA.
Qualified medical expenses also include those for a spouse and dependents. Sunscreen bought for the whole family counts.
Sunscreen is the easy part. Other kinds of sun protection are where the rules change.
Are UV Umbrellas and UPF Products Covered by an FSA or HSA?
Not automatically. UV umbrellas, UPF 50+ clothing and sun hats have everyday uses, so plans usually want proof of medical need, typically a Letter of Medical Necessity.
Administrators treat these as dual-purpose items. An umbrella or a hat can be bought for comfort or style, so a plan wants evidence that it treats, mitigates or prevents a diagnosed condition. Sunscreen skips that test because it is an over-the-counter drug.
What a UV umbrella adds to sunscreen
Shade is a physical barrier, and it needs no reapplication. That matters because the FDA advises reapplying sunscreen at least every two hours, and more often when sweating or swimming.
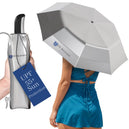
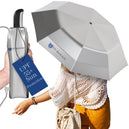
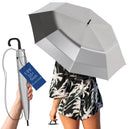
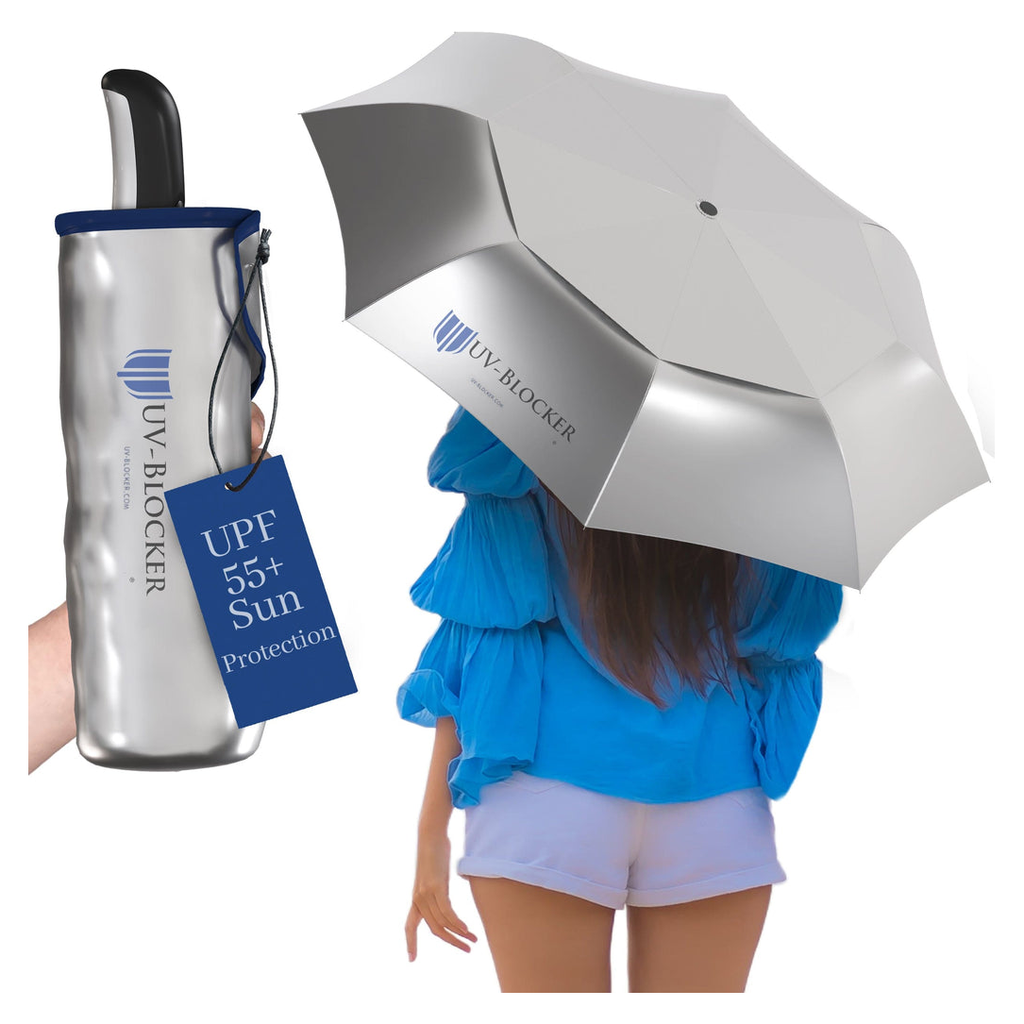
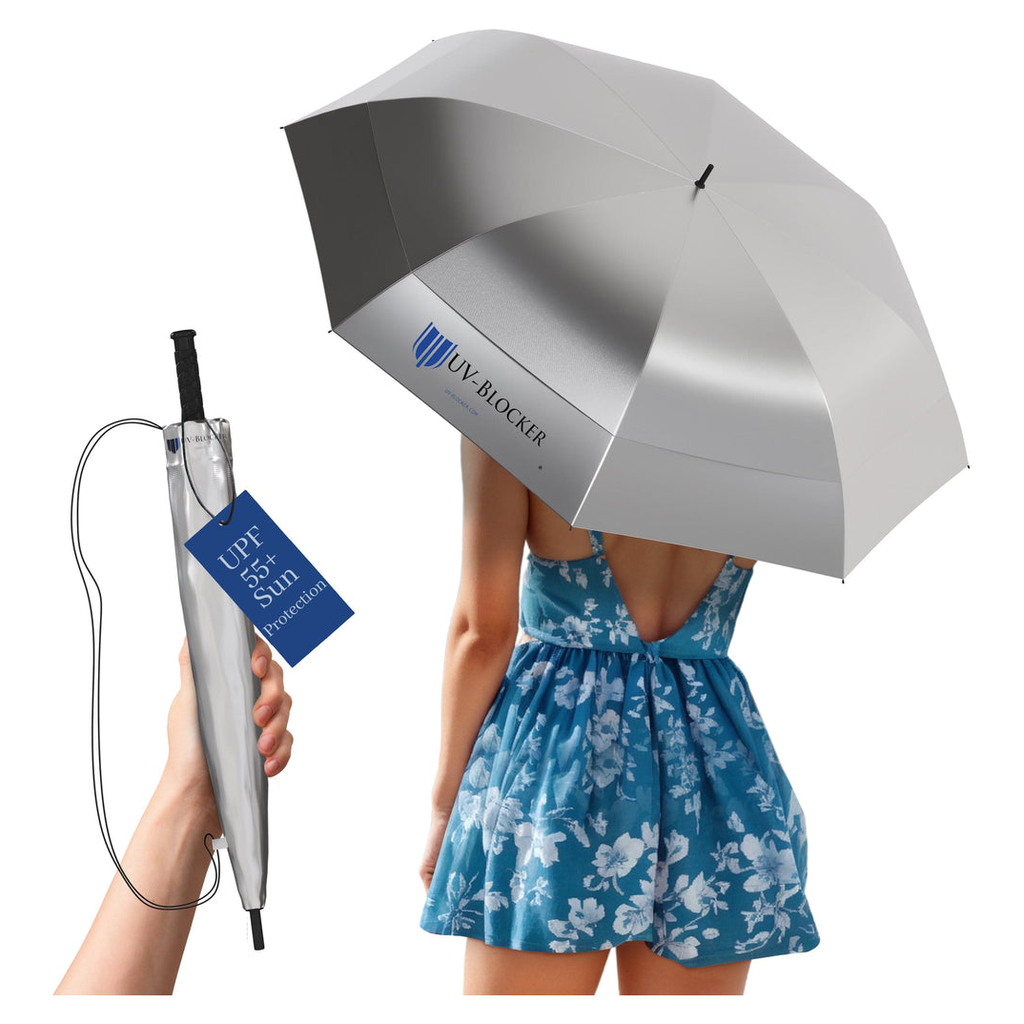
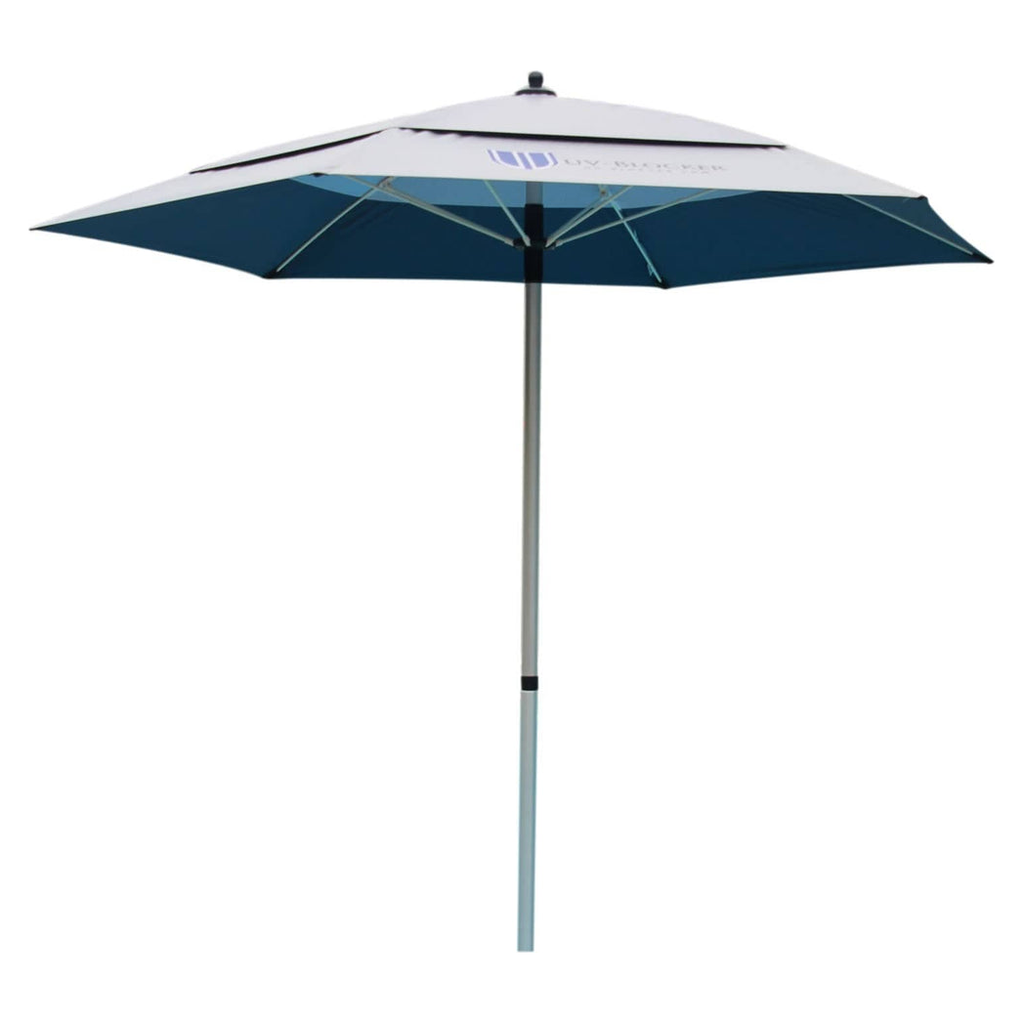
A UV umbrella from UV-Blocker uses Solarteck® reflective silver fabric on the outside with a navy underside. It is rated UPF 50+, and SGS testing to AATCC TM183-2020 found the fabric blocks 100% of UVB and 99.97% of UVA. Every model in the range of UPF 50+ umbrellas uses the same silver-and-navy build.
SPF and UPF measure different things. SPF rates how well sunscreen protects skin, while UPF rates how much UV a fabric lets through; the UPF vs SPF guide explains the difference in detail.
An umbrella works alongside sunscreen, not instead of it. Here is how the main types of sun protection compare:
| Item | FSA/HSA status | What you usually need |
|---|---|---|
| Broad-spectrum SPF 15+ sunscreen | Eligible | Itemized receipt |
| Moisturizer or makeup with SPF, sold as a cosmetic | Depends on the administrator | Check your plan before buying |
| Tanning oil, SPF under 15, or not broad spectrum | Not eligible | Not applicable |
| UV umbrella, UPF 50+ clothing, sun hat | Not automatically eligible | Usually a Letter of Medical Necessity for a diagnosed condition; the administrator decides |
So what is a Letter of Medical Necessity, and who gets one?
When Do You Need a Letter of Medical Necessity?
You need one when an item isn't eligible by itself. A licensed provider writes it to explain how the item treats or prevents a diagnosed condition.
A Letter of Medical Necessity (LMN) typically names the diagnosis, the item and why it is medically needed. The plan administrator, not the seller, decides whether to accept it.
Who commonly has a documented need
People advised to avoid the sun for medical reasons commonly include those with:
- lupus
- a history of skin cancer
- a photosensitizing medication
- radiation therapy after cancer
- vitiligo
A diagnosis does not guarantee approval. That call belongs to the clinician who writes the letter and the plan that reviews it. UV-Blocker's guide to UV umbrellas for medical conditions covers how shade fits into sun protection for several of these conditions.
Keep the letter with your receipts. Administrators can ask to see it, and some want it on their own form.
Here is how paying works at UV-Blocker.
Can I Pay With My FSA or HSA Card at UV-Blocker?
Yes. UV-Blocker accepts HSA and FSA cards at checkout. A short health survey goes to an independent licensed practitioner, who issues a Letter of Medical Necessity if you qualify.
The process runs through UV-Blocker's checkout partner, Truemed:
- Choose an umbrella and pay with your HSA or FSA card at checkout.
- Complete a short health survey. Truemed works with a network of independent practitioners who review eligibility and issue Letters of Medical Necessity to customers who qualify.
- Watch for the letter, which usually arrives within 24 to 48 hours, and keep it for three years.
- If your administrator rejects the payment, contact Truemed. Plans often have detailed requirements, and the fix can be as simple as re-issuing the letter on the administrator's own form.
UV-Blocker does not issue the letter or decide eligibility, and cover still depends on your plan. The same steps are laid out in FSA and HSA payments at UV-Blocker.
Choosing an umbrella
The best sellers are the UV Protection Compact Umbrella ($59.95), the UV Protection Travel Umbrella ($59.95), the Large Folding UV Umbrella ($64.95) and the UV Protection Golf Umbrella ($64.95). Each keeps you up to 15°F cooler than standing in direct sun.
UV-Blocker umbrellas are dermatologist recommended and approved by the Melanoma International Foundation. The criteria doctors use are covered in the guide to choosing a dermatologist-recommended UV umbrella. Founder Ron Walker started UV-Blocker in 2005, two years after a Stage 1 melanoma diagnosis.
Whichever route you take, the deadline matters most.
What Are the FSA Deadline, Grace Period and Carryover Rules for 2026?
FSA money generally expires at plan year end. A plan may offer a grace period (up to 2½ months) or a carryover (up to $680), never both.

Grace period
A grace period gives up to 2½ months after the plan year ends to incur new expenses and pay for them from leftover money, according to IRS Publication 969. For a calendar-year 2026 plan, that runs to March 15, 2027.
Carryover
A carryover lets unused money roll into the next plan year instead. For 2026 plan years, the cap is $680, and anything above it is forfeited.
The figure comes from Rev. Proc. 2025-32. A plan that offers a carryover cannot also offer a grace period.
Neither, plus the run-out period
Some plans offer neither, so unspent money is lost once the plan year ends. Separately, some plans allow a run-out period: extra time to submit claims for expenses already incurred. It does not extend the time to buy, and the plan sets its length.
For reference, the 2026 health FSA contribution limit is $3,400. The 2026 HSA limits are $4,400 for self-only coverage and $8,750 for family coverage under Rev. Proc. 2025-19, and HSAs have no spending deadline.
A five-step year-end checklist
- Check your FSA balance and your plan year end date.
- Ask HR or your administrator whether the plan has a grace period, a carryover or neither.
- Buy qualifying sunscreen (broad spectrum, SPF 15 or higher). No paperwork is needed.
- If you have a qualifying condition, start the Letter of Medical Necessity route early.
- Keep every itemized receipt.
Shopping for someone else? Our sun protection gift guide matches each person on your list to the right umbrella, with prices and holiday order deadlines.
Is Sunscreen FSA Eligible? Frequently Asked Questions
Quick answers to the questions people most often ask about sunscreen, sun protection and their FSA or HSA.
Do I need a prescription to buy sunscreen with my FSA?
No. Since 2020, over-the-counter products, including sunscreen, need no prescription for reimbursement from a health FSA, an HSA or an HRA that covers them.
Is tinted sunscreen or makeup with SPF FSA eligible?
Tinted sunscreen labeled broad spectrum SPF 15 or higher usually qualifies. Makeup and moisturizers sold mainly as cosmetics may be declined, so check with your administrator first.
Can I use my FSA or HSA for my spouse's or kids' sunscreen?
Yes. Qualified medical expenses include those for your spouse and dependents, so broad-spectrum SPF 15+ sunscreen bought for the family can be paid from the account.
Is a UV umbrella HSA eligible?
Not automatically. With a Letter of Medical Necessity for a diagnosed condition, your administrator may accept it, but the administrator makes the final decision, not the seller.
What happens to FSA money I don't spend in time?
It is forfeited, unless your plan has a grace period of up to 2½ months or a carryover of up to $680 for 2026 plan years.
Can a UV umbrella replace sunscreen?
No. Use them together. An umbrella shades you from direct UV without reapplication, while sunscreen protects skin the shade does not reach.
The Bottom Line on Sun Protection and Your FSA
Sunscreen is the simplest FSA or HSA purchase there is, while physical sun protection takes a medical reason and the right paperwork.
- Broad-spectrum SPF 15+ sunscreen needs no prescription and no letter.
- Pay from the right account: a health FSA, an HSA or a covering HRA, not a limited-purpose or dependent care FSA.
- UV umbrellas and UPF products usually need a Letter of Medical Necessity, and the administrator decides.
- Know your plan's rules: a grace period, a carryover or neither.
The quickest win takes about ten minutes: look up your FSA balance and plan year end date today.
For shade that needs no reapplication, UV-Blocker's UV umbrellas can be paid for with an HSA or FSA card at checkout. Small price to pay. Isn't your health worth it?